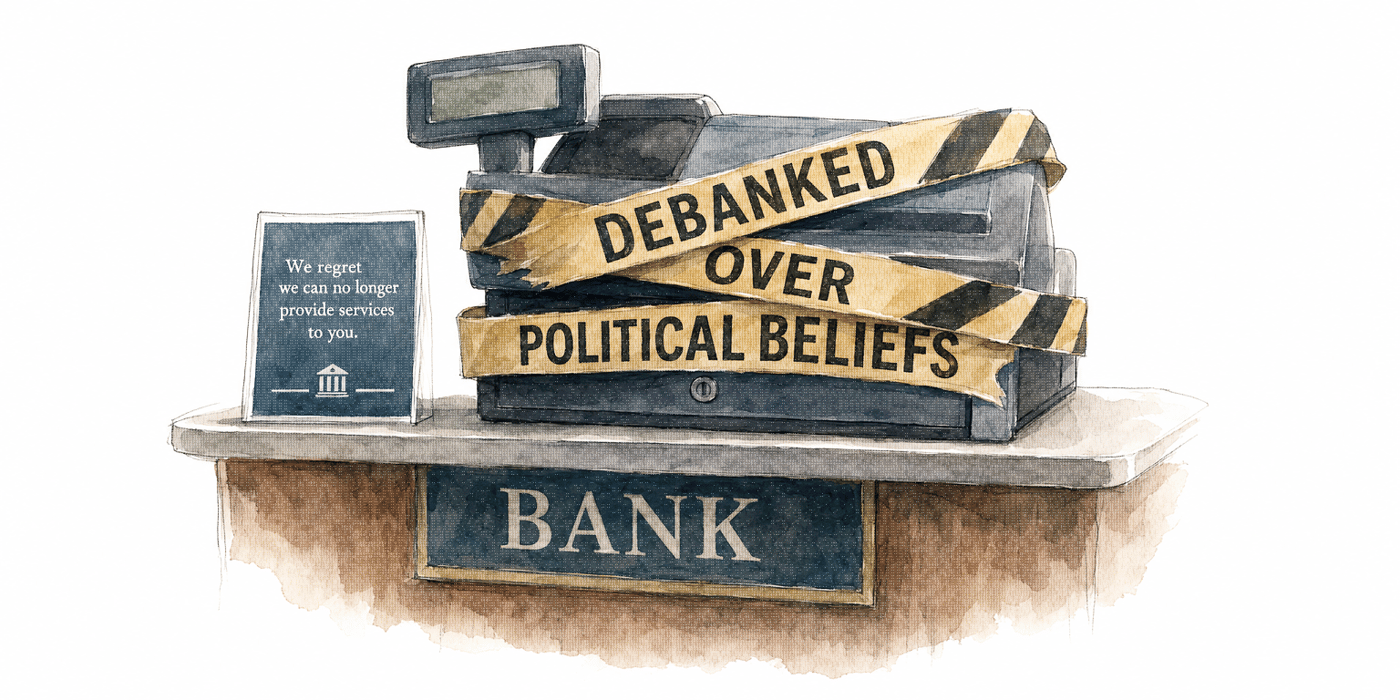

It’s been months in the making, but yesterday’s 47-page report from the Office of the Comptroller of the Currency made clear that the big banks were playing politics with people’s lives and livelihoods.
“Today’s report,” said Comptroller of the Currency Jonathan V. Gould in an accompanying press release, “provides irrefutable evidence that the nation’s largest banks have denied, debanked, and discriminated against customers and lawful businesses.” Gould added, “Americans should have access to financial services regardless of their beliefs, affiliations, or political views. Fair access to financial services is not a mantra — it is a mandate.”
Recall that Donald Trump’s executive order of August 7, 2025, titled “Guaranteeing Fair Banking for All Americans,” sought to put an end to all this. And yesterday’s report is replete with examples of what our nation’s nine biggest banks — JPMorgan Chase Bank, Bank of America, Citibank, Wells Fargo Bank, U.S. Bank, Capital One, PNC Bank, TD Bank, and BMO Bank — were doing.
Among the transgressions: “public and nonpublic policies restricting certain industry sectors’ access to financial services, including those in oil and gas exploration, coal mining or coal-powered plants, firearms or ammunition manufacturing or distribution, construction or operation of detention facilities, the manufacturing, distribution or online retail of tobacco or e-cigarettes, and digital asset activities [i.e. bitcoin].”
Consider JPMorgan Chase’s payment operation, WePay, which closed the account of a merchant selling gear promoting President Trump and the “Make America Great Again brand, saying it promoted “hate, violence, or racial intolerance.”
But not so fast. As The Wall Street Journal reports, “Capital One ... rejected an organization supporting reproductive rights, including abortion access,” with one employee pointing out that its contributions to politicians “are about 95% Democrat.”
The big excuse being bandied about by these Who-Me big banks is “reputational risk” — that is, they took these egregious debanking and denial-of-banking steps in order to protect their squeaky-clean reputations. But the OCC isn’t buying it. “The OCC is considering actions to prevent banks from discriminating against customers or prospective customers on the basis of their political or religious beliefs and to address the problematic role of reputation risk in bank decision-making.”
Reputational risk, eh? You don’t say. Y’know what’s a reputational risk? When one-half of the American people think that our nation’s leading banks are run by a bunch of craven politically motivated Democrat dirtbags. These bank CEOs — the Jamie Dimons and the Brian Moynihans and such — had better thank their lucky stars that Republicans and conservatives don’t behave like Democrats and progressives. We don’t assassinate our political opponents like they do. And we don’t shoot corporate CEOs in the back, even when we think they’re trying to wreck our lives.
And they have wrecked people’s lives. Donald Trump can certainly take care of himself, but he and his family were debanked, not only by Bank of America but by Signature Bank and Deutsche Bank. And John Eastman — the constitutional scholar and former law school dean who was Trump’s leading post-2020 election lawyer — was ruthlessly debanked, twice in the span of several months, first by Bank of America and then, remarkably, by USAA, the bank he’d fled to. All for the high crime of having given constitution-based legal advice to Trump in the aftermath of the rigged 2020 election.
Memo to Big Bank CEOs: If you want to protect your reputation, stop picking political winners and losers, and stop intentionally harming everyday Americans for their political and religious activities, and their lawful business practices.
As the Journal also reports, “In another instance, TD Bank decided against extending a Covid-19 era emergency loan to a nonprofit promoting anti-immigration positions.”
It’s understandable that a sleazy bank might do such a thing. After all, open borders let in all sorts of cheap laborers, which depress the wages of low-end working Americans while making the open-borders Chamber-of-Commerce types really happy.
But that’s not the worst of this particular offense. The Journal continues, “The bank’s decision was influenced in part by [wait for it!] the Southern Poverty Law Center, which had designated the nonprofit a ‘hate group.’” And the SPLC’s name pops up repeatedly in the report as a trusted arbiter of what constitutes a reputationally risky customer.
We can’t make this stuff up.
It’d be interesting to see what the left-right ratio is for those being denied services. My sense is that the Trump administration wouldn’t be pursuing this matter as zealously as it is were there is many left-leaning victims as there are right-leaning victims.
Were the big banks weaponized against Trump and his associates, and more generally against all things MAGA? And were a handful of left-leaning organizations included in these debanking practices as devious a way for the banks to claim they weren’t acting in a partisan manner? It’s hard to say at this point, and we won’t have any crystal clarity until someone does a deep dive into the document dump and produces a right-vs.-left ratio of victims.
But this much we do know: The Trump family was debanked, and John Eastman was debanked, and yet I don’t know of a single leading Democrat who’s been debanked, so there’s that.
Suffice it to say that the banking industry has, by wading into politics, put itself on a slippery slope. Going forward, banks should stick to safeguarding our money and schlepping their credit cards.