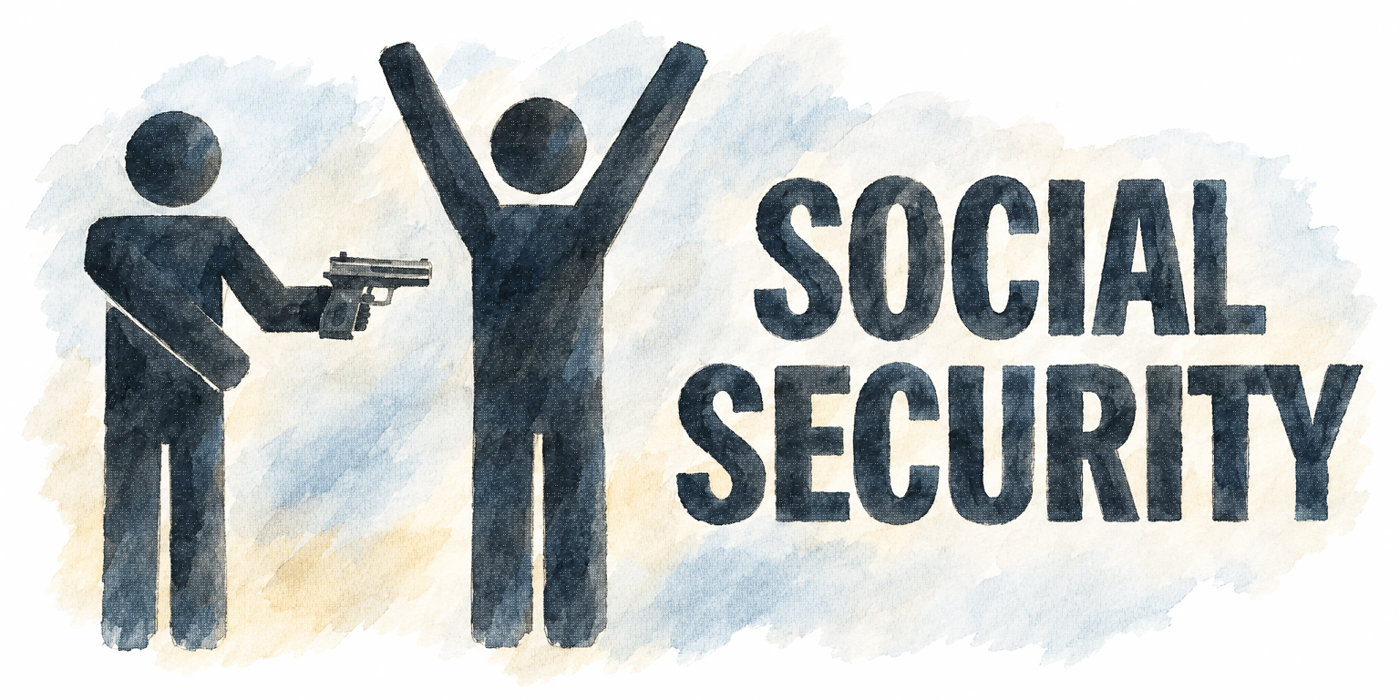

“Social Security: The Reality... a Legal Ponzi Scheme.” That’s the provocative title of a new report written by Wisconsin Republican Senator Ron Johnson, chairman of the Senate Budget Committee.
Unfortunately, he’s right.
“Social Security is a Legal Ponzi Scheme. This term offends most people who have had FICA taxes extracted from their paychecks for decades. But it is an accurate description of how grossly Social Security has been mismanaged over the decades,” Johnson writes in his report.
He explains, “The Securities and Exchange Commission (SEC) defines a Ponzi scheme as ‘an investment fraud that pays existing investors with funds collected from new investors.’ Delete the word ‘fraud’ because Social Security is legally sanctioned, and that’s exactly what Social Security does.”
He continues, “People often say, ‘Don’t touch Social Security, that’s my money.’ Actually, it’s not. Your money was spent to pay current beneficiaries or fund other government programs as soon as it was collected from your paycheck.”
We’ve been saying this for years, so as the great John McClane once said, welcome to the party, pal.
To our readers who depend on Social Security, I get it, and I’m not telling you promises weren’t made, or that no one owes you anything. You paid into the system, and now you expect the return you were promised. It’s the law. That’s well and good.
But generations of politicians in Washington, DC, lied to you.
Before the above conclusions, Johnson’s report begins with historical facts:
The Social Security Act of 1935 was signed into law by President Roosevelt providing “Federal old-age benefits” to qualified workers who reached the age of 65. At the time, life expectancy was 62. FICA tax of 1% was first deducted and collected from workers’ paychecks in 1937. The first monthly benefits were paid in 1940. ...
For most of its existence, the program collected more in FICA tax revenue than it paid in benefits. That surplus was never invested in an asset that had value outside the federal government. Instead, the surplus was spent along with other tax revenue coming into the general fund, and special issue Treasury Bonds were placed in a four-drawer file in Parkersburg, West Virginia — the Social Security Trust Fund.
To an outside investor those bonds would have value. To the U.S. Government, they are simply an intergovernmental bookkeeping entry with no real value.
To put it mildly, the problem is enormous. His report continues:
Unfortunately, politicians from both parties — either from their own ignorance or willful deception — have misled the American public for decades by promoting the fiction that their entire payroll deduction for Social Security was being invested in a real asset (often using the term “lockbox”) to earn compound interest yielding an adequate amount for retirement. Nothing could be further from the truth.
Most Americans believe their FICA payroll taxes are comparable to contributions to a 401(k) or private pension plan. To prove how wrong this assumption is, consider what happens in the case of the untimely death of a worker with no spouse or dependents. If that worker has a 401(k) plan, whatever balance remains can be willed to a beneficiary. In the case of Social Security, nothing can be bequeathed.
Because the Social Security portion of the FICA tax is quite high (currently 12.4%), too many Americans also think their contributions should provide for a comfortable retirement, and accordingly do not save additional and sufficient amounts in a 401(k) or private pension plan. They are then surprised at the inadequate amount Social Security actually pays, creating enormous pressure on the political process to increase benefits. Politicians have responded to that pressure and exacerbated the problem.
Johnson also points out the previously noted demographic issues, such as rising life expectancy and the changing workers-retiree ratio.
Given all that horrible news, what can be done? Johnson’s report isn’t exactly optimistic. He recounts some of the might-have-beens, such as what would have happened if previous generations of political leaders had actually invested the money instead of spending it. He recalls how George W. Bush was “saved by demagogues” for suggesting we let young workers choose such investments.
But ultimately, “Once a Ponzi scheme begins to collapse, it can’t be fixed. It can only be liquidated.”
Social Security is projected to be insolvent in 2032, a little more than five years from now. That year, “the Social Security deficit is projected to be $511 billion — 21% of the total projected federal deficit of $2.4 trillion.” The only way to fix it, Senator Johnson says, is to rein in overall deficits so we can continue funding the program.
I certainly expect the political and legal consequences of allowing Social Security to collapse will inspire our intrepid representatives to do whatever it takes to cook the books and keep it running. So nobody panic. It’s all going to be just fine!